










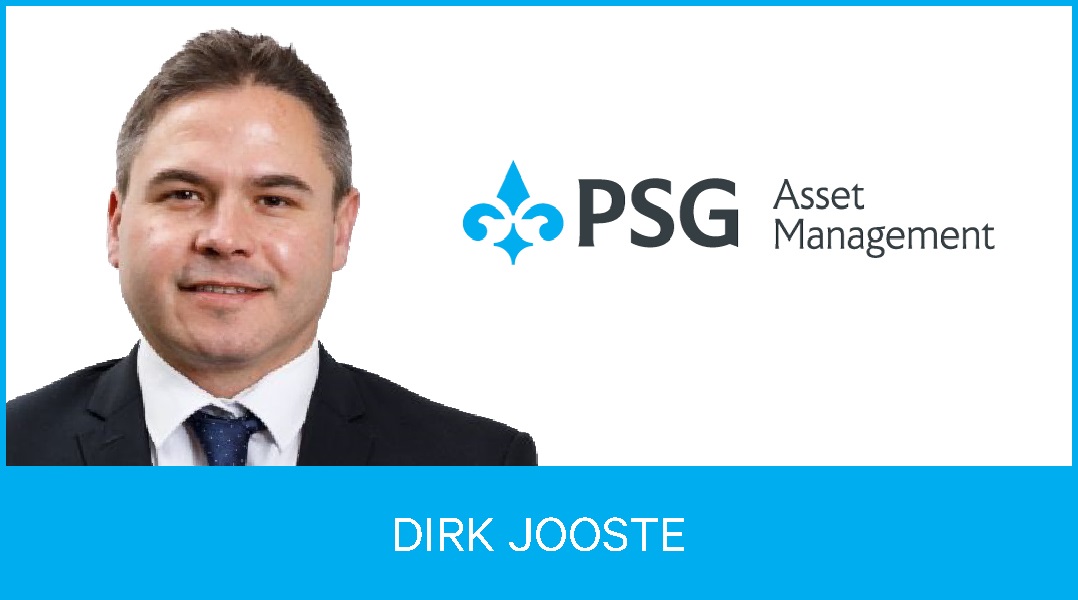
Dirk Jooste, Fund Manager at PSG Asset Management
For many investors, their retirement savings will be their biggest and most important investment, and one that needs to underpin and support their lifestyle for many years, possibly decades, in retirement. Poor long-term investment outcomes on retirement savings can have major consequences for investors’ financial well-being and quality of life in retirement.
The default option when it comes to retirement savings tends to be a traditional balanced fund that complies with Regulation 28 of the Pension Funds Act. But while the legislation provides a broad framework to encourage appropriate asset allocations and levels of risk-taking in pre-retirement savings, this does not mean that all balanced funds are managed in the same way. Far from it. And looking ahead, we believe how funds are managed will matter greatly for the outcomes investors achieve.
We believe we are seeing the unwinding of massive imbalances in the macro environment which have accumulated since the Global Financial Crisis (GFC). We are likely seeing the end of an era of cheap money, with profound implications for the correlations between asset classes and returns investors can expect to see from these assets into the future.
Navigating a regime change in markets is tricky in itself, but it is further complicated by today’s frothy valuations and high levels of index concentration in stock markets. We believe that the initial price paid for an investment remains one of the key determinants of the long-term returns investors are likely to see. Overpaying for an asset is a sure-fire way to hamstring performance in the long run. However, it can be very difficult for investors to buck the trend and avoid the popular stocks dominating most indices, particularly when these are propelled into headlines daily on the back of exuberance around the artificial intelligence (AI) theme.
It is easy to lose sight of the fact that not all companies involved as early participants in technology build-outs are destined to be winners in the long run. Even though the technology can be transformative to society at the aggregate level, many companies involved in developing the technology are likely to fail or underperform. Excitement about new technologies drives capital expenditure (capex) driven market booms, but as more entrants pour money into developing the new technology, returns start to diminish, and a bust generally ensues. Simply cast your mind back to the numerous examples during the Technology, Media and Telecom (TMT) bubble and the dotcom-era bust in the early 2000s. Further back in history, railroad bubbles in the 1880s and 1890s tell the same story. There is nothing new about excitement over technology, or the speculative fervour that often follows. At the height of market exuberance, it can be hard for investors to imagine that anything else could reward them – yet this is often the point at which thoughtful diversification is needed most.
With a fundamental recalibration underway in markets and equity valuations looking stretched, it is imperative that funds are managed with a changing environment in mind. The strategies that have worked well since the GFC look set to experience headwinds in the coming decade and beyond. Herein lies the challenge for many investors ‒ and the balanced funds that they rely on to grow their wealth and set them up for success in retirement.
Many managers have approached multi-asset fund management by dividing the funds into the underlying asset classes and managing these in isolation. In an era when global bonds could be counted on to offset periods of negative performance in global equities, such an approach produced acceptable outcomes in many scenarios. But in an environment of higher, less predictable inflation, global bonds can no longer be relied on to act as an automatic portfolio diversifier. Instead, it will be crucial to evaluate the attractiveness of each security on its own merits, to include it only when it is attractive in its own right, and with a specific portfolio role in mind. Where each asset class is managed in isolation, it is impossible to take a holistic view of the hidden relationships between securities and the resultant overall portfolio risk position.
Moreover, inflation protection may need to be sought from non-traditional sources – such as industries characterised by supply-side constraints, real assets, and energy and commodity stocks. Many of these areas have proved extremely unpopular since the GFC, and the energy and commodity sectors have shrunk precipitously as a share of equity indices. Energy and materials, for example, made up around 20% of the MSCI ACWI at the end of 2007 but account for only about 8% today, while technology has grown from around 10% to a third of the index. Those constructing their portfolios with reference to today’s tech-heavy, AI-dominated indices are therefore likely to be lacking in exactly the areas best positioned to provide valuable portfolio protection and diversification.
ENDS